Stellantis Weighs Moving Ram Heavy-Duty Truck Production from Mexico to Michigan Amid Tariff Pressures

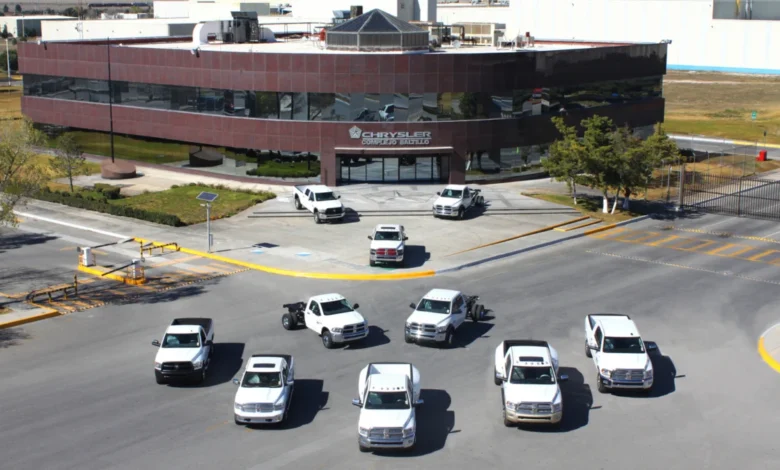
Automotive giant Stellantis is currently engaged in high-stakes feasibility discussions with its supply chain partners regarding a potential, massive realignment of its North American manufacturing footprint. The multinational automaker is examining whether the prevailing macroeconomic environment, heavily defined by aggressive trade tariffs on Mexican-made motor vehicles, justifies the immense capital expenditure required to relocate Ram heavy-duty pickup truck production from its facility in Saltillo, Mexico, to its historic manufacturing campus in Warren, Michigan.
This strategic re-evaluation underscores the profound friction currently facing international automakers operating under modern trade frameworks. For years, major automotive corporations leveraged regional free trade agreements and localized cost advantages to optimize production lines across the United States, Mexico, and Canada. However, the reintroduction of significant tariffs on vehicles imported from south of the border has fundamentally altered the financial calculus. Stellantis must now determine whether the traditional cost-savings associated with Mexican manufacturing can survive the direct financial impact of border tariffs, or if long-term profitability is best secured by bringing heavy-duty truck assembly back to American soil.
Background Context of the Shift to Saltillo and the Warren Facility
The historical context of both manufacturing hubs highlights the scale of any potential relocation. The Saltillo Truck Assembly Plant, occupying approximately 212,850 square feet of operational floor space, has been a cornerstone of the company’s heavy-duty vehicle strategy. Operational since 1995, the Saltillo facility shifted its primary focus to heavy-duty truck production in 2009. Today, it serves as the exclusive production home for the robust Ram 2500, 3500, 4500, and 5500 models distributed throughout the United States market, a lineup that recently expanded to incorporate specialized variants such as new Ram sport trucks.
Conversely, the Warren Truck Plant in Michigan represents a vastly different scale of industrial infrastructure. Spanning an immense 3.31 million square feet, the Warren facility has been continuously operational since 1938, serving as an iconic symbol of American automotive heritage. In its current configuration, the Warren plant is dedicated primarily to the production of the Jeep Grand Wagoneer. This operational focus leaves the facility with substantial excess manufacturing capacity—space that could theoretically accommodate the entire assembly footprint of the Ram heavy-duty truck line without requiring the construction of new greenfield facilities.
Despite the physical capacity available in Michigan, transitioning an assembly line of this magnitude is far from a simple logistics exercise. The evaluation process requires exhaustive consultations with component suppliers to weigh the cumulative cost of importing tariff-burdened parts from Mexico against the local procurement costs of sourcing those same components from U.S.-based suppliers. Furthermore, the capital expenditure required to decommission, transport, and re-install complex heavy-duty assembly tooling across international borders represents a major financial hurdle that must be justified to corporate stakeholders and shareholders alike.
Economic Realities: Labor, Tariffs, and Cross-Border Supply Chains
The core dilemma facing Stellantis executives revolves around a complex balancing act of labor costs, supply chain logistics, and direct taxation. Historically, building vehicles in Mexico offered automakers significant labor cost advantages. These operational savings were a primary factor in the strategic decision to allocate production of high-margin heavy-duty trucks to the Saltillo facility, particularly in the wake of significant labor negotiations in the United States.
The most recent master labor agreement between Detroit automakers and the United Auto Workers (UAW), ratified following historic negotiations, secured substantial wage increases and benefits for American union workers. While this contract provided labor stability and a clear operational runway extending through its expiration on April 30, 2028, it also permanently elevated the baseline labor expenses associated with domestic vehicle assembly.
To offset these domestic labor realities, automakers have historically leaned heavily on cross-border trade. Statistical data from the U.S. Department of Commerce illustrates the profound integration of the North American automotive ecosystem: in 2024 alone, the United States imported more than $86 billion worth of motor vehicles and in excess of $63 billion worth of automotive components from Mexico.
However, the imposition of tariffs—reaching up to 25% on Mexican-made automotive imports—erodes the financial margins that previously justified southern manufacturing. When executives evaluate the economics, they must contrast the penalty of continuous tariff payments on Mexican-assembled trucks with the alternative expenses of domestic production: higher prices from U.S. parts suppliers and the elevated wage structures of UAW labor in Michigan. Adding further competitive pressure to the equation is the industry landscape: domestic rivals Ford Motor Company and General Motors currently manufacture their respective heavy-duty pickup lines entirely within the United States, presumably maintaining healthy profit margins under the same regulatory and tax conditions that Stellantis is now navigating. This competitive benchmark is especially critical as Stellantis prepares for future product rollouts, including the highly anticipated 2027 Ram Power Wagon, featuring advanced powertrain options like the Cummins turbo-diesel engine.
Political Variables and Regulatory Uncertainty
Beyond standard balance-sheet arithmetic, corporate strategy in the modern automotive sector is inextricably linked to geopolitical currents. The longevity and structure of the current tariff regime remain primary variables in the strategic planning of multinational corporations. Stellantis leadership must project how trade policies may evolve over the medium and long term, factoring in the political climate leading up to the 2028 presidential election and the potential durability of protectionist trade measures.
Supply chain adaptations resulting from tariffs are rarely instantaneous or easily reversed. Sourcing components locally in the United States requires long-term supplier development, quality validation, and contractual commitments. Executives must assess whether supply chain reorientations prompted by current trade policies will prove to be permanent structural shifts or temporary disruptions. If an automaker undertakes the massive capital investment of repatriating vehicle production to Michigan, only to see trade policies shift again under a subsequent administration, the financial consequences could be severe.
Pricing Power and Market Competitiveness
Another critical dimension of the decision-making process is consumer pricing power within the highly competitive full-size truck segment. The American pickup truck market is fiercely contested, with brand loyalty and price sensitivity playing massive roles in consumer purchasing decisions.
Industry analysts note that if established competitors like General Motors and Ford maintain stable pricing structures due to their existing domestic manufacturing footprints, Stellantis will face severe market constraints. The corporation would have limited ability to pass the cost of Mexican tariffs directly onto consumers without risking market share erosion. Consequently, the imposition of tariffs directly diminishes the anticipated profitability of the Saltillo operations. Whether trucks continue to roll out of Mexico burdened by heavy import taxes or are assembled in Michigan utilizing more expensive domestic labor and parts, profit margins are destined to compress unless mitigated by operational efficiencies or strategic price adjustments.
Implications and the Path Forward
The deliberations currently underway at Stellantis corporate headquarters represent a microcosm of the broader challenges confronting the global automotive industry as it recalibrates to a fragmented and protectionist trade landscape. The choice between maintaining manufacturing operations in Mexico under punitive tariff structures or repatriating heavy-duty truck production to the historic Warren Truck Plant in Michigan is fraught with multi-million-dollar complexities.
As supplier consultations proceed, industry observers will be watching closely for concrete indicators of intent. The ultimate decision will serve as a bellwether for how traditional automakers plan to navigate the intersection of international trade policy, domestic labor agreements, and regional supply chain integration in the years leading up to 2028 and beyond. Whether Stellantis chooses to absorb the ongoing costs of cross-border trade or commits to a major industrial homecoming in Michigan, the outcome will reshape the future of one of North America’s most iconic automotive nameplates.