The artificial intelligence industry has undergone a fundamental structural transformation, pivoting away from a one-dimensional race centered purely on model intelligence toward a high-stakes, multi-layered infrastructure war. As the economics of the AI sector face intense margin compression and escalating operational expenditures, industry leaders have quickly realized that maintaining a foothold in a single layer of the technology stack is no longer a viable strategy for long-term survival.
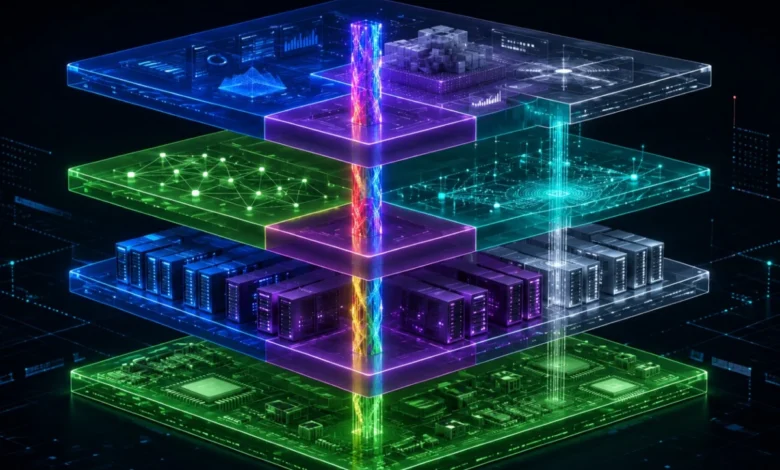
The modern generative AI stack comprises four distinct tiers. At the foundational base lies hardware, consisting of physical accelerators and specialized graphics processing units (GPUs). Above that rests the compute cluster layer, which includes the massive cloud servers and gigawatt-scale data centers necessary to house and run the hardware. The third tier is the model layer, populated by advanced foundational architectures such as OpenAI’s GPT series and Anthropic’s Claude. Finally, the uppermost tier is the application layer, featuring consumer and enterprise-facing end-user interfaces like ChatGPT and specialized development environments like Cursor.
Dominating just one of these segments no longer provides an adequate competitive moat. Consequently, the most successful market participants are aggressively expanding vertically—pushing both upward and downward from their original starting positions to protect profit margins, secure critical supply chains, and capture new streams of enterprise value.
The Evolution of the AI Infrastructure War
For the first several years of the contemporary generative AI boom, the competitive landscape was defined primarily by algorithmic breakthroughs. Tech giants and specialized startups alike raced to scale parameter counts, improve reasoning capabilities, and achieve benchmark dominance. However, as frontier models matured, the financial realities of training and inference set in. The cost of running advanced artificial intelligence at scale exposed the vulnerabilities of single-layer business models.
Hardware shortages, energy constraints, and the soaring cost of third-party cloud computing forced a strategic reckoning. Companies that originally focused exclusively on software development discovered that they were entirely at the mercy of silicon manufacturers and cloud hyperscalers. Conversely, hardware and cloud providers recognized that selling infrastructure alone left them exposed to commoditization if they could not capture software-level utility and user engagement.

This realization triggered a massive convergence across the industry. Today, model creators are designing custom silicon and building proprietary data centers, application developers are fine-tuning in-house models using proprietary user-experience data, and hardware giants are releasing open-source models to fuel unrelenting demand for their physical products.
Model-First Pioneers Confront the Reality of Hardware Costs
Pure-play model companies face severe financial pressures. While developing a frontier model requires billions of dollars in upfront computational investment, the operational phase—known as inference—is where the real margin compression occurs. Relying on traditional suppliers and third-party cloud infrastructure has proven increasingly unsustainable for top-tier AI labs.
In response, leading model developers are aggressively pushing down the stack into hardware and compute. OpenAI, aiming to bypass the premium pricing associated with dominant GPU suppliers, partnered with Broadcom to develop its custom AI inference chip, code-named Jalapeño. Targeted for commercial deployment by late 2026, this initiative underscores how even the premier software laboratories must venture into custom silicon design to maintain economic viability at scale.
Anthropic encountered a parallel infrastructure bottleneck, realizing that legacy cloud providers could not provision sufficient power grids fast enough to meet its skyrocketing energy demands. To secure its future computational capacity, Anthropic entered into a landmark $50 billion infrastructure partnership with neocloud provider FluidStack. Operating independently of legacy enterprise IT constraints, the partnership focuses on constructing custom multi-gigawatt data centers in Texas and New York designed specifically for massive AI training workloads.
Meanwhile, xAI chose to bypass traditional cloud ecosystems entirely. Under the leadership of Elon Musk, the company developed the Colossus supercomputer, effectively transforming its parent organization, SpaceX, into a massive hyperscaler. SpaceX now controls its infrastructure from the ground up, not only supporting its own internal workloads but also renting surplus compute capacity to external competitors. This dynamic is highlighted by high-profile agreements, such as Anthropic’s multi-billion-dollar commitments for access to Colossus compute capacity.
Application-Layer Innovations and the Value of User Experience
Critics of the application layer have historically dismissed consumer-facing wrappers—thin software interfaces built over third-party APIs—as transient products destined for obsolescence once frontier labs release native features. However, the trajectory of AI-powered development environments like Cursor has thoroughly debunked this thesis, proving that deep workflow integration and proprietary user-experience (UX) data constitute formidable, defensible moats.

Cursor initially emerged as an Integrated Development Environment (IDE) that allowed programmers to route prompts to various third-party frontier models. By processing millions of real-world coding sessions, the platform accumulated an expansive dataset capturing specific developer behaviors, iterative workflows, and complex interaction patterns. Leveraging this proprietary asset, Cursor’s developer, Anysphere, introduced Composer 2.5, a fine-tuned iteration of the open-weights Kimi K2.5 model.
By training Composer 2.5 on its own UX telemetry, Cursor established an in-house model capable of handling routine implementation tasks faster and at a fraction of the cost of external frontier APIs. Developers now utilize Composer 2.5 for standard code generation while reserving expensive frontier models strictly for complex architectural reasoning.
This deep integration into professional workflows made application-layer pioneers exceptionally attractive to infrastructure giants seeking direct outlets for their massive compute capacity. In June 2026, SpaceX acquired Anysphere in a $60 billion all-stock transaction. The mega-deal illustrates how base-layer infrastructure titans are extending their reach to the very top of the stack to secure permanent user touchpoints and guarantee steady consumption of their computational power.
Cloud Hyperscalers Expand Upward and Downward
Traditional cloud hyperscalers—including Amazon, Microsoft, and Google—initially positioned themselves as landlords of the digital age, renting out GPU clusters to finance the AI ambitions of specialized labs. Today, however, these tech conglomerates are executing aggressive full-stack strategies, expanding upward into proprietary software applications and downward into custom-designed silicon.
Amazon has steadily built a hardware moat beneath Amazon Web Services (AWS) through the development of its proprietary Trainium and Inferentia chips. By offering custom silicon alternatives, Amazon reduces its reliance on third-party hardware vendors while delivering improved operating margins to enterprise developers building on its cloud.
Microsoft pursued a different avenue, leveraging its vast distribution network across Windows and Microsoft 365 to capture immense value at the application layer. By embedding generative AI capabilities directly into ubiquitous enterprise workflows, Microsoft maintains a permanent pipeline to global users regardless of which underlying model achieves technical superiority. To bridge the gap between its Azure compute infrastructure and its consumer software suite, Microsoft has also rolled out proprietary model families, including the open-weights Phi series and the closed MAI models. While these proprietary models do not always match the absolute frontier capabilities of external competitors, they provide Microsoft with cost-effective alternatives for everyday enterprise tasks.

Hardware Titans Pivot to Open-Source Models
Nvidia has cemented its position as the most valuable physical infrastructure provider in the global technology sector by supplying the high-performance accelerators that power modern AI workloads. However, to safeguard long-term hardware utilization and defend against the rising tide of custom application-specific integrated circuits (ASICs) like Amazon’s Trainium and OpenAI’s Jalapeño, Nvidia has quietly established a presence at the model layer.
In late 2025, Nvidia released the Nemotron 3 suite as fully open-source, providing public access to model weights, training datasets, and architectural recipes. This strategy diverges sharply from industry norms, where even open-source contributors frequently withhold core training data. Nvidia can uniquely absorb the costs of open-sourcing advanced models because the widespread proliferation of open-source AI directly stimulates massive physical hardware demand.
When developers download transparent, high-performance open-source models for custom enterprise fine-tuning, they immediately require substantial computational power and GPU accelerators. By championing open-source development, Nvidia ensures that the global ecosystem continues to scale on its proprietary hardware architecture rather than migrating exclusively to closed systems running on custom internal silicon.
The Complete Vertical Integration of Google
Among the major technology conglomerates, Google stands out as the sole participant natively integrated across all four layers of the artificial intelligence stack simultaneously. Google’s proprietary Tensor Processing Units (TPUs) represent a formidable alternative to traditional GPU hardware, anchoring its strength at the base layer. Its Google Cloud Platform functions as a top-tier provider of enterprise compute, while the Gemini model family consistently competes at the absolute frontier of artificial intelligence research. At the application tier, Google commands unrivaled global distribution through its core Search engine, the Android operating system, and the Workspace productivity suite.
This comprehensive vertical integration generates a powerful, self-sustaining data flywheel. Billions of daily user interactions across Google’s consumer applications directly inform and refine the training pipelines for subsequent model generations, which are subsequently processed on proprietary hardware infrastructure. Market analysts note that this level of seamless integration provides Google with operational efficiencies and defensive moats that pure-play competitors find difficult to replicate.
The Strategic Retrenchment at Meta
Meta’s initial entry into the contemporary AI race relied on a classic economic playbook: commoditize your complement. By distributing its Llama foundational models as open-source weights, Meta sought to neutralize the pricing power of frontier labs like OpenAI and Anthropic, protecting its massive consumer distribution across platforms like Facebook, Instagram, and WhatsApp.

However, this strategy encountered significant limits. While open-sourcing frontier models accelerated broader industry innovation, it simultaneously compressed Meta’s own competitive advantage window. Rivals eagerly utilized Meta’s open weights to bootstrap their own architectures, rapidly matching and occasionally exceeding Meta’s proprietary research capabilities.
This dynamic culminated in industry-wide debates regarding model performance and benchmarking integrity, prompting Meta to reevaluate its approach to foundational development. The company subsequently introduced proprietary, closed-source multimodal architectures specifically designed for commercial monetization. Meta’s strategic pivot illustrates a vital lesson of the modern AI economy: massive financial commitments and abundant compute capacity cannot guarantee a sustainable competitive advantage if foundational intellectual property is entirely surrendered to industry rivals.
Implications for the Future of the AI Economy
The boundaries separating the distinct tiers of the artificial intelligence stack have permanently dissolved. Companies originating at the model layer are investing billions in custom silicon and energy infrastructure to survive mounting operational costs. Hardware manufacturers are releasing frontier models to stimulate persistent demand for physical accelerators. Application developers are fine-tuning proprietary models using user-experience data to protect profit margins from API price fluctuations.
As the industry matures beyond its initial speculative phase, it has become evident that operating within a single isolated layer is insufficient for long-term economic viability. The ultimate victors of the AI arms race will be those organizations capable of executing seamless vertical integration across every tier of the technological stack—controlling the hardware, managing the compute infrastructure, training the foundational models, and capturing the end-user relationship at the application edge.