What Paint Sampling Data Reveals About America’s Rapidly Warming Interior Design Palettes

For generations, the narrative surrounding residential paint trends has been shaped by hindsight. Paint manufacturers, industry forecasters, and interior designers regularly declare colors of the year, establish emerging palettes, and publish exhaustive predictions regarding the hues that will soon dominate the market. Yet, these declarations typically reflect what people ultimately purchase or what experts aspire to see on residential walls, offering little insight into the tentative, exploratory phases of home design. A new metric, however, aims to change how the design industry understands consumer preference by analyzing not what people buy, but what they seriously consider along the way.
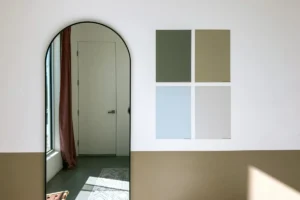
That behavioral shift forms the core of the inaugural Samplize American Paint Color Report. By tracking millions of peel-and-stick paint samples ordered across the United States during the first six months of 2024, 2025, and 2026, the report offers an unprecedented look at consumer decision-making. Spanning major industry heavyweights such as Benjamin Moore, Farrow & Ball, and Sherwin-Williams, the data captures the exact moments when homeowners test various shades side by side, evaluating conflicting undertones and crossing brand boundaries before committing to a final gallon of paint.
The Mechanics of Paint Sampling and Behavioral Analysis
The methodology behind the report sheds light on a previously opaque stage of interior design. According to Makenna Lutz, partnerships lead at Samplize, analyzing the sampling phase provides a holistic view of the consumer mindset that traditional point-of-sale data simply cannot capture.
"Analyzing this sampling stage reveals three crucial things: the full shortlist a person actually weighed, which colors get tested against each other, and how that shortlist spans brands," Lutz explains.
Historically, paint sales data has told retailers what left the shelves, but it failed to capture the near-misses—the dark greens, subtle grays, or vibrant pinks that were taped to a drywall and ultimately rejected in favor of a safer neutral. By examining millions of multi-brand sample shortlists, analysts can map out the cognitive and aesthetic tug-of-war homeowners experience during a renovation project. This granular approach bridges the gap between expert trend forecasting and grassroots consumer behavior, providing paint manufacturers and interior designers with concrete metrics on how tastes evolve in real time.
The Great Warming: A Comprehensive Shift in Color Temperature
The most striking finding across the three-year dataset is a definitive, accelerating departure from cool color palettes. Warm colors grew nearly three times faster than cool colors throughout the study period, culminating in a dominant market share. Warm hues now account for 69.4 percent of all paint samples tested through Samplize, up significantly from 64.3 percent just two years prior.
This thermal migration is further emphasized by the composition of consumer shortlists. Half of all American shortlists examined in the recent data contain zero cool colors—an increase from 43 percent at the inception of the study. This indicates that homeowners are not merely experimenting with warm accents while retaining a cool foundation; rather, they are building entire project shortlists exclusively within the warm color spectrum.
Depth Defies Expectations: The Rise of Deep Warm Tones
An intuitive assumption might link this widespread warming trend to a nationwide embrace of light, airy interiors—a return to the safe havens of stark white, pale beige, and creamy ivory. However, the empirical data reveals a much more complex architectural psychology.
"The genuine surprise was in the split by depth," Lutz notes, addressing the counterintuitive trajectory of the data. "We expected the warming to show up as lightening—it didn’t. Warm outgrew cool at every depth, and the deepest warm tones grew fastest of all, roughly six times faster than deep cool tones."
This divergence shatters the long-held industry assumption that warm interiors must inherently be bright and minimal. Homeowners are actively seeking cocooning, moody spaces, but they are achieving this drama through thermal saturation rather than cool pigmentation.
On one end of the spectrum, delicate blush-toned plasters and warm creams are thriving. Products such as Farrow & Ball’s Setting Plaster, Benjamin Moore’s Proposal, and Sherwin-Williams’ Malted Milk represent a softer, tactile approach to interior walls. Concurrently, at the opposite end of the depth scale, intensely saturated warm hues are experiencing a massive surge. Benjamin Moore’s Classic Burgundy—one of the darkest colors analyzed in the study—grew at a pace comparable to the lightest pastels. This proves that the modern appetite for dark, dramatic interiors remains robust, even as the emotional temperature of that drama shifts away from cool navy blues and charcoal grays toward rich, earthy warmth.
The Brown Renaissance and the Evolution of Neutrals
Nowhere is this thermal shift more apparent than in the resurgence of brown, a color family that has historically faced polarizing public opinion in American interior design. Brown shades grew faster than any other color family during the study period, expanding from 9.2 percent of shortlists to 13.4 percent.
However, the vanguard of this brown renaissance bears little resemblance to the heavy, saturated chocolates and rustic terracottas of past decades. Instead, the growth is being propelled by sophisticated, muted hybrids. Sherwin-Williams’ Warm Stone and Urbane Bronze, Farrow & Ball’s London Clay, and Benjamin Moore’s Smokey Taupe are leading the charge. These shades occupy the nebulous, highly adaptable territory of greiges, warm grays, and stone-inspired neutrals. By straddling the line between gray and brown, these colors offer consumers a seamless transition away from the sterile cool grays that defined the 2010s, introducing subtle earthy complexity without overwhelming a space.
Green Stabilizes as a Modern Staple
While browns and warm tones experienced rapid growth, other color families demonstrated structural stability. Green, which enjoyed a meteoric rise in popularity during the pandemic and post-pandemic residential design boom, has successfully transitioned from a transient trend to an established permanent fixture in the American palette.
Appearing consistently in 34.6 percent of shortlists, green has firmly cemented its status as a neutral alternative. The spectrum of greens being tested remains exceptionally wide, spanning from soft, desaturated sages and architectural mosses to deep, moody botanical greens. This sustained presence suggests that homeowners view nature-inspired greens not as a fleeting design fad, but as a foundational element that bridges the gap between interior living spaces and the natural world.
Temperature-Exclusive Shortlists and Consumer Decisiveness
Beyond individual color families, the Samplize report offers fascinating insights into consumer psychology and decision-making architecture. The data reveals that two-thirds of all color shortlists contain samples originating from a single temperature group. Specifically, half of all shortlists are entirely warm, while only about a third of consumers mix warm and cool shades during their evaluation process.
This stark polarization underscores a high degree of visual clarity among renovators. Rather than hedging their bets by testing contrasting temperatures side by side, homeowners appear to enter the sampling phase with a preconceived emotional direction for their space.
Furthermore, signs indicate that this warming palette is becoming increasingly chromatic. While neutrals and earth tones dominate the baseline percentages, smaller color families are experiencing explosive percentage growth from modest starting points. Pink and red have emerged as the fastest-growing color families overall, while the combination of "warm and deep" stands out as the fastest-growing intersection of temperature and depth in the entire dataset.
Broader Industry Implications and Future Outlook
While three years of sample data cannot definitively predict the exact visual landscape of American walls a decade from now, the macroeconomic and design implications of these findings are profound. The residential paint market, traditionally driven by top-down directives from color corporations, is increasingly reflecting a bottom-up psychological evolution.
The data demonstrates that contemporary homeowners are rejecting the stark, cool-toned minimalism that characterized urban and suburban interiors for over a decade. In its place, they are cultivating spaces defined by emotional resonance, tactile depth, and organic warmth. Whether through the quiet subtlety of a plaster-pink cream, the grounded sophistication of a warm greige, or the theatrical embrace of a deep burgundy, the American interior design ethos is undergoing a fundamental thermal realignment. As manufacturers and designers look toward future collections, the mandate from the consumer base is clear: the future of color is warm, deep, and unapologetically complex.
Related posts: